
Investment Review and Outlook
Credit Spreads Leaked Wider, but It Was Rates That Pressured Returns
The main story during the third quarter was not credit or spreads but rather a sharp repricing of interest rates pushing yields on the Index over six-percent. Before rates began to move to center stage in September, the credit market’s focus was mostly on new corporate bond supply, with a record August pushing the summer tally over $500 billion, up 30 percent Y/Y, in what is typically a slower period. Hyperscalers7 continued to increase their weightings in the Index, with two issuers now among the top 15 by market value and two among the top eight. While U.S. banks remain six of the largest ten issuers, if hyperscalers continue to issue bonds at this pace they may challenge U.S. banks for top Index spots within a couple of years. While issuer and sector concentration is a challenge and causes hand-wringing, corporate bond investors have become accustomed to this with the Banking sector.8
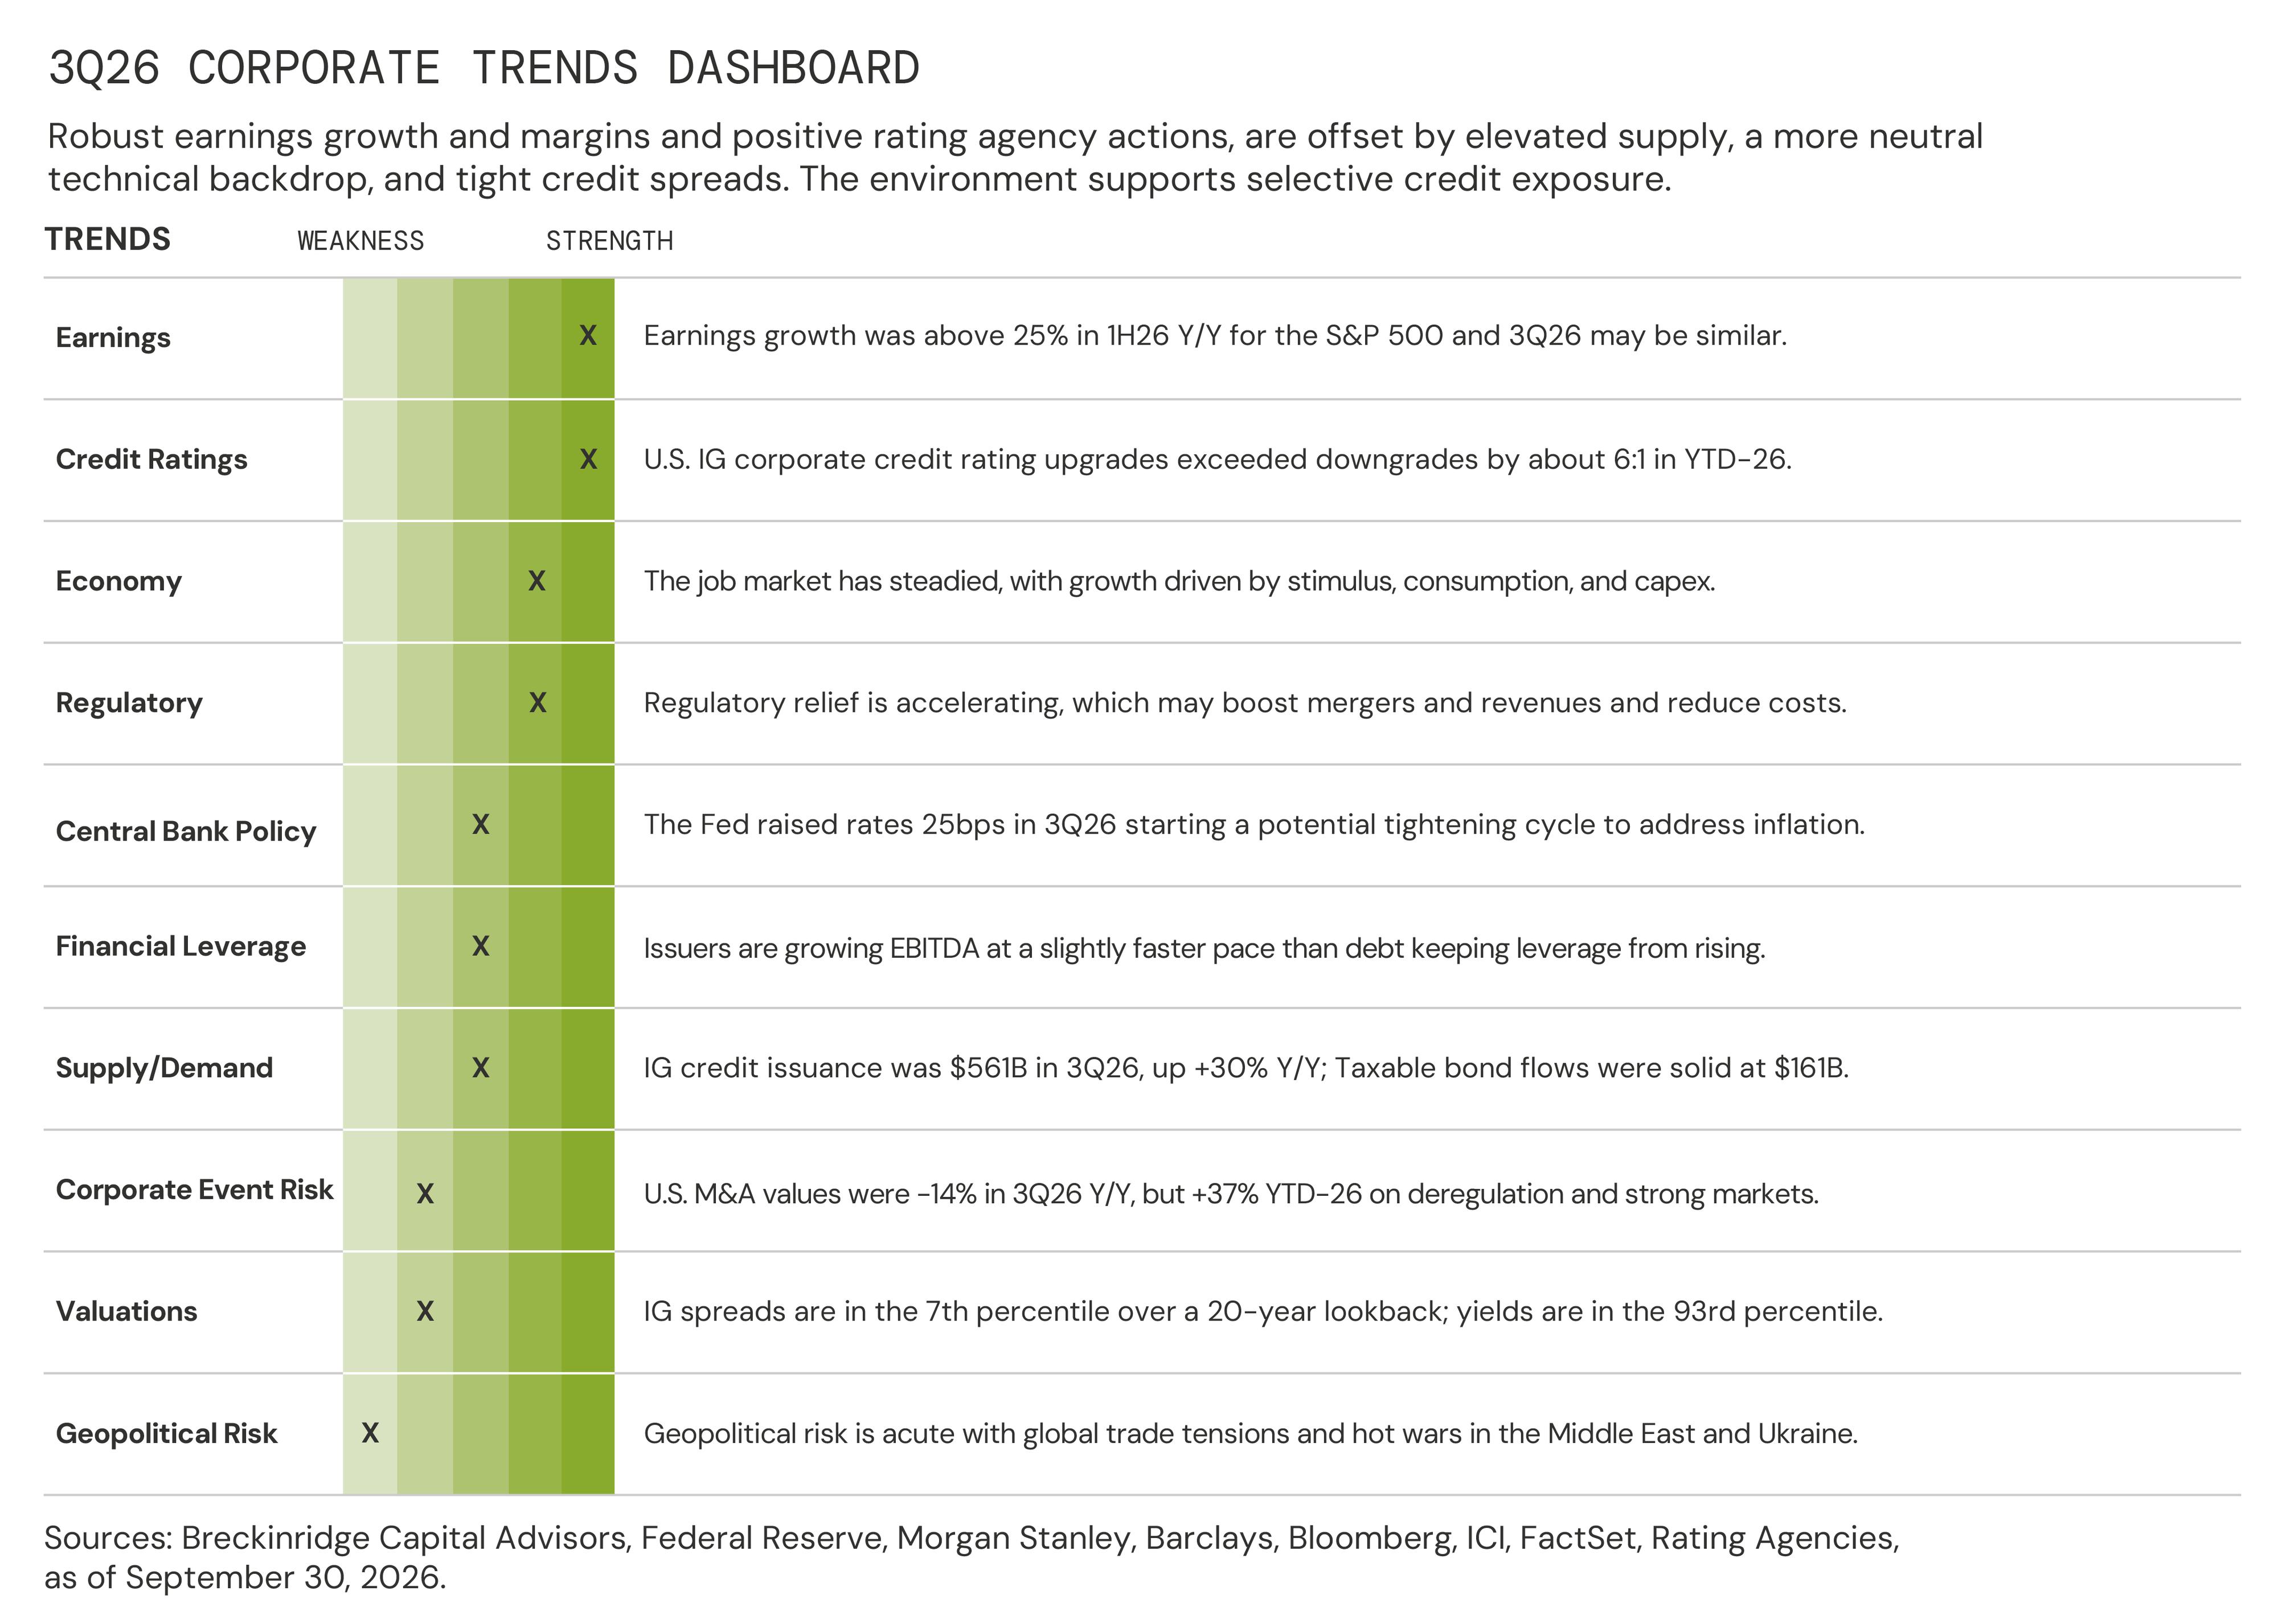
Credit spreads widened 6bps in the third quarter after 14bps of tightening in the second quarter. Strong earnings and economic growth, favorable rating actions, and equity market gains supported credit spreads, while elevated supply and interest rate volatility9 were clear headwinds. Sectorwise, underperformance continued in Technology (+8bps), Retailers (+10bps), Media Entertainment (+10bps), and Cable Satellite (+24bps), where the hyperscaler issuers reside.
With rising commodity prices, oil specifically, Energy (-3bps) and Basic Industry (-1bp) continued to outperform. As of 3Q26, credit spreads are back to the 7th percentile over a 20-year look-back, with full valuations necessitating careful selection. Despite a negative total return this quarter, well above average yields in the 93rd percentile are driving strong demand and fund flows.10
The Breckinridge Investment Committee’s base case macro outlook is for real gross domestic product (GDP) growth to return towards trendline levels. Strong AI-related capex and resilient consumer spending have pushed growth higher, though nominal wage growth is on a decelerating trend at around three percent. We expect one additional Federal Reserve (Fed) interest rate hike in 2026 and another in 1H2027. Geopolitical developments add uncertainty and are a downside risk to the outlook.
Well above-average yields, solid investor demand, and stable-to-improving credit fundamentals are offset by tight spreads, debt-funded AI capex, and high supply, driving a modest overweight to the corporate sector with a defensive posture. A broad repricing of interest rates means that elevated current yields and higher income generation can provide a larger cushion for total returns, should rates move higher. We view the income proposition for credit as attractive with the Index yield around six-percent at 3Q26.11
Valuations: Tight Spreads, Well Above-Average Yields
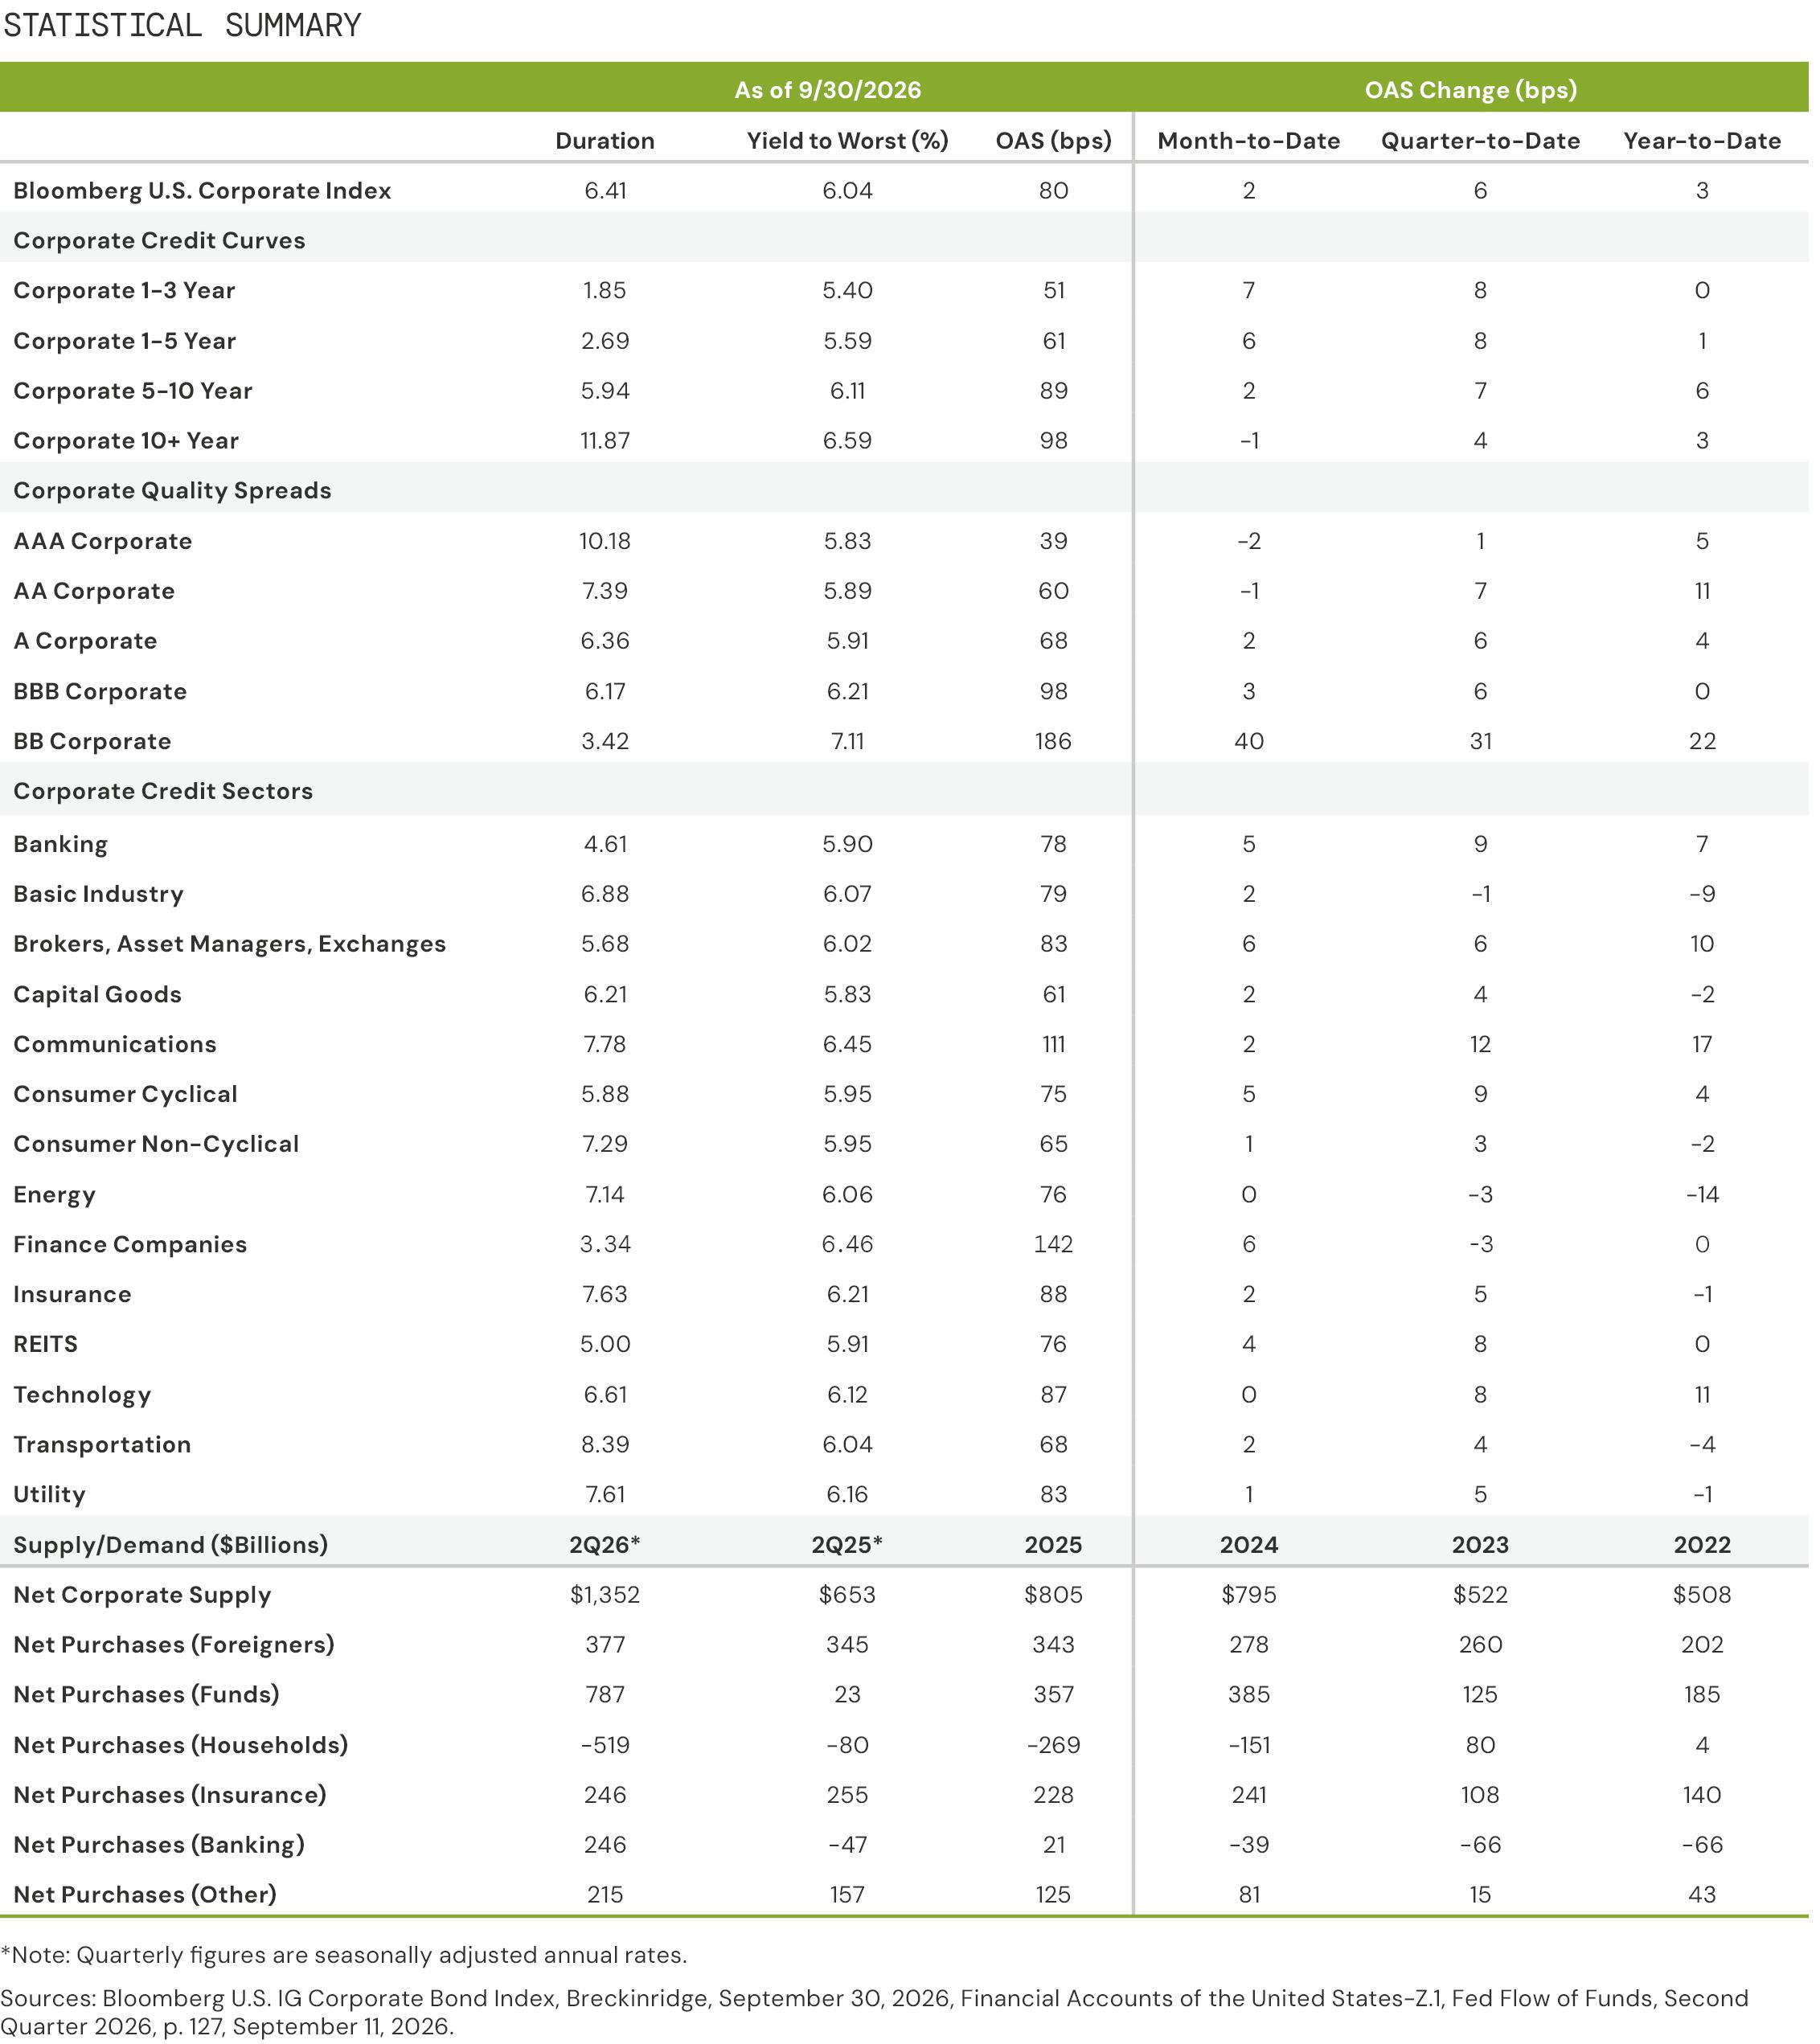
Corporate spreads were 6bps wider in 3Q26, closing at an option-adjusted spread (OAS) of +80bps (See Figure 1).12 Credit spreads argue for a defensive stance, while high yields are supportive of valuations and fund flows. Given the sharp moves higher in Treasury yields, the Index’s total return was -394bps in the third quarter, while the excess return was -14bps.13

Across credit quality tiers, the AA bucket, with its concentration of hyperscalers, continued to underperform, with spread widening of 7bps. The A/BBB Industrial quality-spread differential was flat at 35bps, with a z-score of negative 2.0 compared to the five year average.14 Spreads on short (1-3 year), intermediate (5 year), and long corporate (10+ year) BBG indices widened by 8bps, 7bps, and 4bps, respectively, as credit curves flattened.
Unlike the first half of the year, there was minimal performance dispersion across Financials (+8bps), Industrials (+5bps), and Utilities (+5bps) in 3Q26. While spreads are compressed, Financials continue to offer incremental spread to comparable duration and quality Industrial bonds. Credit spreads on Finance companies, specifically Business Development Companies (BDCs), tightened by 9bps and have more than recovered from sharp underperformance from earlier in the year. Cable Satellite and Media Entertainment both underperformed in the third quarter, widening 24bps and 10bps, respectively, on elevated debt-funded capex and merger and acquisition (M&A)-related supply.15
Technicals: Elevated Supply and Robust Demand
We view credit technicals as neutral. An active July ($162 billion), a record August ($171 billion), and an as-expected September ($228 billion) pushed the summer credit issuance tally to over $500 billion, up over 30 percent Y/Y (See Figure 2). IG bond issuance in 3Q26 was driven by refinancing activity, AI capex-related issuance, and robust bank supply. Gross supply was $561 billion in 3Q26. Net issuance, after $318 billion of redemptions, was $243 billion. Taxable bond fund flows were $161 billion in 3Q26 and net foreign buying of corporates was $97 billion in 3Q26.16

Financials dominated supply, issuing $232 billion in the third quarter followed by Communications ($85 billion) and Consumer Discretionary ($56 billion).17 The market value of the Technology Index at 10.7 percent is the third largest sub-sector of the IG market, up from 9.7-percent one-year ago.18 These figures exclude non-U.S. dollar ($USD) bond issuance, project financing, operating and finance leases, asset-backed deals, private IG borrowing, equity issuance, and other sources being tapped by hyperscalers to fund AI capex.19
Fundamentals: Steady Leverage, Near Record Margins
Strong earnings growth and record high margins support stable-to-improving credit fundamentals. Corporate balance sheets are well positioned to manage higher financing costs. Earnings growth was above 25 percent in 1H26 Y/Y for the S&P 500 and 3Q26 may be similar.20 U.S. IG credit rating upgrades exceeded downgrades by about 6:1 year-to-date (YTD).21

Hyperscalers’ capex estimates are projected near $1 trillion in 2026 and approach $1.5 trillion in 2027.22 Debt-funded AI-related capex is high, although exposed sectors have partially mitigated credit and leverage impacts by issuing hybrids and common equity. Sharply rising capex is a risk to AI-exposed sectors such as Technology, Communications, and Utilities, although high credit ratings, strong balance sheets, and regulated business models mitigate added leverage in these sectors, respectively.
M&A values were down 14 percent in 3Q26 Y/Y but were up 37 percent YTD on deregulation and strong markets.23 Regulatory relief is accelerating, which may boost mergers and revenues and reduce costs. M&A activity is rising and may strain metrics if heavily debt funded, although, having tapped financing sources to date, have been balanced. IG issuers have grown debt and earnings before interest, taxes, depreciation, and amortization (EBITDA) at the same pace, keeping leverage steady over the trailing five-year period.24
Bank credit looks stable, with peak earnings power, strong market-sensitive revenues, steady growth in net interest income, and benign asset quality. In fact, S&P Global Ratings, a relatively conservative rating agency for large banks in our view, upgraded a U.S. Global Systemically Important Bank (G-SIB) after years of governance and growth challenges.25 Inflation and high interest rates are pressuring lower-income consumers, which may have a larger knock-on effect on subprime auto and credit card delinquencies. With the material rise in Treasury and mortgage-backed securities (MBS) yields, unrealized losses on bond portfolios will increase but should remain below the 2022-2024 period and durations are shorter.26 Still, there will be an impact on capital ratios as a result.
With high short-term interest rates, low-cost bank deposits are at risk, as higher-interest alternatives do exist. The $7.9 trillion in money-market funds27 and $4.1 trillion in certificates-of-deposit (CDs)28 demonstrate that short-term money, in our view, will find higher interest rates without draining the banking system of deposits, which are nearly $20 trillion.29
In the future, Agentic AI may be able to optimize interest rates in excess cash or high-yield saving accounts but in the present there is friction, in our view.30 Would most close a bank account and open another at a virtual bank, redo monthly and quarterly bills, mortgage, home equity loan, and credit cards, and direct deposits to earn an extra 10 to 15bps on the $8k31 of cash in the median checking or savings account, when CDs or other higher-interest-bearing accounts are a reasonable alternative? Perhaps Agentic AI would find banks that pay the highest deposit rates. We know from experience it may not always be prudent to squeeze out a few extra basis points in banks that are perhaps most at risk during a bank run or economic recession.32
[1] The BBG U.S. IG Corporate Bond Index is an unmanaged market-value-weighted index of IG corporate fixed-rate debt issues with maturities of one year or more. You cannot invest directly in an index.
[2] The BBG U.S. IG Corporate Bond Index, Option-Adjusted Spread (OAS) vs Treasury Curve, Breckinridge, 9/30/26.
[3] Ibid.
[4] Investment Company Institute (ICI), Weekly Combined Estimated ETF and Long-Term Taxable Bond Flows, 9/30/26.
[5] Treasury International Capital (TIC), TIC Data for July 2026, Net Corporate Bond Cross-Border Flows, 9/18/26.
[6] Barclays FICC Research, U.S. Investment Grade Credit Metrics – Q2 26 Update: Stable Metrics, 9/22/26.
[7] Hyperscalers are large cloud service providers that own and operate outsized global data centers that offer on-demand computing, storage, and networking resources.
[8] Banking sector is 22% of the market value of the, twice that of Tech (10.7%) BBG U.S. IG Corporate Bond Index.
[9] Merrill Lynch Option Volatility Estimate (MOVE) Index is a gauge of interest rate volatility in the U.S. Treasury Market. The MOVE Index had a correlation (R) of 0.61 to the BBG U.S. IG Corporate Bond Index from 9/30/03 – 9/30/26. R was 0.76 from 9/30/23 – 9/30/26, with periods of time when the correlation (R) rose to 0.81.
[10] Breckinridge, A percentile rank is the percentage of values that fall at or below a specific score, 9/30/2006-9/30/2026.
[11] Bloomberg U.S. IG Corporate Bond Index, Breckinridge, 9/30/26.
[12] The BBG U.S. IG Corporate Bond Index, OAS vs. Treasury Curve, Breckinridge, 9/30/26.
[13] Ibid.
[14] A z-score is a statistical measurement that indicates how far away a data point is from the mean of a dataset, measured in terms of standard deviations. It standardizes a raw score, allowing for comparisons between different datasets or populations.
[15] Ibid.
[16] Treasury International Capital (TIC), TIC Data for July 2026, Net Corporate Bond Cross-Border Flows, 9/18/26.
[17] Bloomberg, U.S. IG Corporate League Tables, Sector Breakdown by Volume, 3Q26, 9/30/26.
[18] Bloomberg U.S. IG Corporate Bond Index, Breckinridge, 9/30/26.
[19] Barclays Research, Data Center Bond Comp Sheet, AI Data Center Bonds Outstanding are $112 billion, 9/11/26.
[20] Earnings are projected to grow 22 percent in 3Q26, Earnings Insight, FactSet, 9/25/26.
[21] Bloomberg, U.S. IG Agency rating upgrades exceeded downgrades by 6:1 YTD-26, RATT <GO> on BBG, 9/30/26.
[22] Morgan Stanley Global Credit Strategy, What We Are Watching, The State of AI Financing, 10/5/26.
[23] Bloomberg, Merger, and acquisitions were up 37 percent YTD-26, MA <GO> on BBG, 9/30/26.
[24] Barclays Research, Credit Strategy, US Investment Grade Credit Metrics – Q2 26 Update, 9/22/26.
[25] S&P Global Ratings upgraded Wells Fargo & Co.'s issuer credit rating to 'A-' from 'BBB+' on 9/29/26.
[26] FDIC Quarterly Banking Profile, Unrealized Gains and Losses on Investment Securities, pp. 4, 2Q 2026.
[27] Investment Company Institute (ICI), $7.9 trillion was held in U.S. money market funds on 9/30/26.
[28] Federal Reserve data, $4.1 trillion was held in U.S. bank certificates of deposits on 9/30/26.
[29] Federal Reserve Bank of St. Louis, $19.6 trillion was held in commercial bank deposits on 9/30/26.
[30] Apollo Global Management, The Daily Spark, Is an Agentic Bank Run Coming? Torsten Slok, 9/27/26.
[31] Federal Reserve Survey of Consumer Finance, Median cash in checking or savings accounts is $8k, 7/2026.
[32] Wall Street Journal, What Happened with Silicon Valley Bank?, 3/14/23.
Request # 97556 (10/8/2026)
DISCLAIMER:
The content is intended for investment professionals and institutional investors.
This material provides general information and should not be construed as a solicitation or offer of services or products or as legal, tax, or investment advice. Nothing contained herein should be considered a guide to security selection, asset allocation, or portfolio construction.
All information and opinions are current as of the dates indicated and are subject to change. Breckinridge believes the data provided by unaffiliated third parties to be dependable, but investors should conduct their own independent verification prior to use. Some economic and market conditions contained herein have been obtained from published sources and/or prepared by third parties, and in certain cases have not been updated through the date hereof.
There is no assurance that any estimate, target, projection, or forward-looking statement (collectively, “estimates”) included in this material will be accurate or prove to be profitable; actual results may differ substantially. Breckinridge estimates are based on Breckinridge’s research, analysis, and assumptions. Other events that were not considered in formulating such projections could occur and may significantly affect the outcome, returns or performance.
Not all securities or issuers mentioned represent holdings in client portfolios. Some securities have been provided for illustrative purposes only and should not be construed as investment recommendations. Any illustrative engagement or sustainability analysis examples are intended to demonstrate Breckinridge’s research and investment process.
Yields and other characteristics are metrics that can help investors in valuing a security, portfolio, or composite. Yields do not represent performance results, but they are one of several components that contribute to the return of a security, portfolio, or composite. Yields and other characteristics are presented gross of advisory fees.
All investments involve risk, including loss of principal. No investment or risk management strategy, including diversification, can guarantee positive results or risk elimination in any market.
Past performance is not indicative of future results. Breckinridge makes no assurances, warranties, or representations that any strategies described herein will meet their investment objectives or incur any profits. Performance results for Breckinridge’s investment strategies include the reinvestment of interest and any other earnings, but do not reflect any brokerage or trading costs a client would have paid. Results may not reflect the impact that any material market or economic factors would have had on the accounts during the time period. Due to differences in client restrictions, objectives, cash flows, and other such factors, individual client account performance may differ substantially from the performance presented.
Actual client advisory fees may differ from the advisory fee used to calculate net performance results. Client returns will be reduced by the advisory fees and any other expenses incurred in the management of their accounts. For example, an advisory fee of 1 percent compounded over a 10-year period would reduce a 10 percent return to a 9 percent annual return. Additional information on fees can be found in Breckinridge’s Form ADV Part 2A.
Index results are shown for illustrative purposes and do not represent the performance of any specific investment. Indices are unmanaged and investors cannot directly invest in them. They do not reflect any management, custody, transaction, or other expenses, and generally assume reinvestment of dividends, income, and capital gains. Performance of indices may be more or less volatile than any investment strategy.
There is no guarantee that the strategies or approaches discussed will achieve their objectives, lower volatility or be profitable. All investments involve risk, including loss of principal. Diversification cannot assure a profit or protect against loss. No investment or risk management strategy can guarantee positive results or risk elimination in any market.
Fixed income investments have varying degrees of credit risk, interest rate risk, default risk, and prepayment and extension risk. In general, bond prices rise when interest rates fall and vice versa.
Equity investments are volatile and can decline significantly in response to investor reception of the issuer, market, economic, industry, political, regulatory, or other conditions.
Breckinridge believes the data provided by unaffiliated third parties, including rating agencies, to be reliable but investors should conduct their own independent verification prior to use. Some economic and market conditions contained herein have been obtained from published sources and/or prepared by third parties, and in certain cases have not been updated through the date hereof. All information contained herein is subject to revision. Any third-party websites included in the content has been provided for reference only, and does not necessarily indicate an endorsement.
BLOOMBERG® is a trademark and service mark of Bloomberg Finance L.P. and its affiliates (collectively “Bloomberg”). Bloomberg does not approve or endorse this material or guarantees the accuracy or completeness of any information herein, or makes any warranty, express or implied, as to the results to be obtained therefrom and, to the maximum extent allowed by law, neither shall have any liability or responsibility for injury or damages arising in connection therewith.
The S&P500 Index (“Index”) and associated data is a product of S&P Dow Jones Indices LLC, its affiliates and/or their licensors and has been licensed for use by Breckinridge. © 2025 S&P Dow Jones Indices LLC, its affiliates, and/or their licensors. All rights reserved. Redistribution or reproduction in whole or in part are prohibited without written permission of S&P Dow Jones Indices LLC. For more information on any of S&P Dow Jones Indices LLC’s indices please visit www.spdji.com. S&P® is a registered trademark of Standard & Poor’s Financial Services LLC (“SPFS”) and Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC (“Dow Jones”). Neither S&P Dow Jones Indices LLC, SPFS, Dow Jones, their affiliates nor their licensors (“S&P DJI”) make any representation or warranty, express or implied, as to the ability of any index to accurately represent the asset class or market sector that it purports to represent and S&P DJI shall have no liability for any errors, omissions, or interruptions of any index or the data included therein.


Subscribe to Insights
Sign up to receive curated insights directly in your inbox.


